Small business owner comparing a QuickBooks Profit and Loss report showing a profit with a bank balance showing less cash.

Your QuickBooks Says You’re Profitable. So Where Is All the Cash?

Your QuickBooks Profit and Loss report says your business made money last month. That’s good news.

But when you look at your bank account, the balance tells a very different story.

Where did all that profit go?

This is one of the most confusing situations small-business owners face, and it doesn’t necessarily mean your QuickBooks is wrong. When it comes to QuickBooks profit vs. cash flow, the two numbers measure different things.

Profit and cash flow are not the same thing.

Understanding the difference can help you avoid cash shortages, make smarter spending decisions, and get more value from your bookkeeping.

QuickBooks Profit vs. Cash Flow: What’s the Difference?

Your Profit and Loss report shows your business’s income and expenses over a selected period. Cash flow shows how money actually moves into and out of your business. Those numbers can be very different.

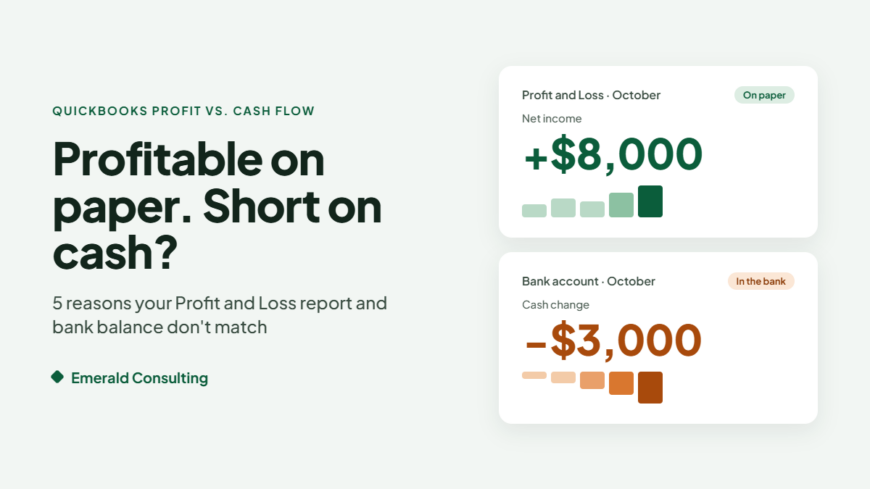
For example, imagine your business completes $20,000 worth of work in October and has $12,000 in expenses. On an accrual-basis Profit and Loss report, that could mean $8,000 in profit.

But what if customers have only paid $9,000 of those invoices? If you’ve already paid most of those expenses, your bank account could be down about $3,000 in a month that shows $8,000 in profit.

Your business may be profitable on paper while still struggling to cover payroll, rent, and other bills. The difference is timing, and timing matters when bills are due.

As we mentioned in our mid-year bookkeeping review, a business can show a profit and still feel tight on cash. Here’s why that happens.

5 Reasons Your QuickBooks Profit Doesn’t Match Your Bank Balance

1. Customers Haven’t Paid Their Invoices

A sale is not always the same as money in the bank.

If your business uses accrual accounting, QuickBooks generally records income when it is earned, even when the customer hasn’t paid yet. That means unpaid invoices can contribute to your reported profit while your bank account is still waiting for the actual deposit.

If you run your Profit and Loss report on a cash basis, unpaid invoices won’t show up as income. The other reasons below still apply.

What to check in QuickBooks:

Run your Accounts Receivable Aging report or Open Invoices report, and look for invoices that are 30, 60, or 90 days overdue.

A business can have strong sales and still experience cash shortages when customers are slow to pay.

2. Loan Payments, Credit Card Payments, and Sales Tax Use Cash Without Reducing Profit

Suppose your business makes a $1,000 monthly loan payment. That money leaves your bank account, but the entire payment does not necessarily appear as an expense on your Profit and Loss report.

Typically, the principal portion reduces the loan liability on your Balance Sheet. The interest portion is recorded as an expense. So you can spend $1,000 in cash while reporting only the interest as an expense.

Paying down a business credit card works the same way. The purchases were already recorded as expenses when they happened. The payment itself reduces the card balance, not your profit.

Sales tax is similar. The sales tax you collect from customers isn’t income. It’s money you’re holding for the state. When you send that payment, cash leaves your account, but your profit doesn’t change.

That’s normal accounting. But it can surprise business owners who expect their Profit and Loss report to explain every dollar leaving the bank.

3. You Bought Inventory, Equipment, or Other Assets

Maybe you bought a new computer, vehicle, or piece of equipment. Your bank account shows the payment.

But depending on the purchase and its accounting treatment, QuickBooks may record it as an asset rather than immediately recognizing the entire amount as an expense. The cost may be recognized over time through depreciation or another appropriate accounting treatment. Your tax professional can help determine how specific purchases should be handled.

Inventory works in a similar way. If you sell products, the inventory you buy typically sits on your Balance Sheet as an asset until it’s sold. Only then does its cost show up on your Profit and Loss report. Stocking up before the holidays can drain cash weeks or months before those costs appear as expenses.

The result? Less cash in the bank without an equivalent immediate reduction in reported profit.

This is one reason your Balance Sheet matters just as much as your Profit and Loss report.

4. Owner Draws Reduce Cash, Not Business Profit

Business owners sometimes transfer money from their business account to their personal account.

For certain business structures, those transfers are recorded as owner draws or distributions rather than operating expenses. The money leaves the bank, but it does not reduce net profit on the Profit and Loss report.

How owner payments should be recorded depends on the business’s legal and tax structure. Owner draws, shareholder distributions, and wages are not interchangeable.

If you’re unsure how these transactions should appear in QuickBooks, it’s worth checking with your bookkeeper and tax professional.

5. Your Bookkeeping Has Errors or Missing Transactions

Sometimes the difference between profit and cash flow is perfectly legitimate. Other times, the problem is your bookkeeping.

Duplicate income, missing expenses, incorrectly recorded transfers, or transactions assigned to the wrong accounts can distort your financial reports. Bank feeds make transaction entry easier, but they don’t guarantee accurate bookkeeping.

If your accounts haven’t been reconciled recently, start there.

Our previous article, 5 QuickBooks Cleanup Problems to Fix Before Year-End, explains several common issues worth investigating before December.

3 QuickBooks Reports Every Business Owner Should Review

You don’t need to become an accountant to understand your business finances. But you should know what your most important QuickBooks reports are telling you.

1. Profit and Loss: Are You Making Money?

Your Profit and Loss report shows income, expenses, and net income for a selected period.

Review it monthly. Look for changes in revenue, rising expenses, and differences from previous months.

Also check whether you’re viewing the report on a cash or accrual basis. That setting can change when certain income and expenses appear.

2. Balance Sheet: What Do You Own and Owe?

Your Balance Sheet shows assets, liabilities, and equity. It can help explain why your cash balance and net income are different.

Review bank balances, credit cards, loans, accounts receivable, inventory, and other significant balances. If something looks unusual, investigate rather than assuming the report is correct.

3. Statement of Cash Flows: Where Did the Money Go?

This report helps explain the movement of cash through your business. It organizes cash activity into operating, investing, and financing activities.

That distinction is important. A profitable business might use cash to repay debt or purchase equipment. Those transactions affect cash differently than they affect reported profit.

Depending on your QuickBooks Online plan, you can find the report under Reports by searching for Statement of Cash Flows. Intuit provides instructions in its official guide: How to Run a Statement of Cash Flows in QuickBooks Online.

Remember that these reports are only as reliable as the transactions behind them.

October Is a Good Time to Check Your Cash Flow Before Year-End

With the fourth quarter underway, this is an excellent time to review your business finances.

You may be planning equipment purchases, holiday expenses, employee bonuses, inventory purchases, or other year-end spending. Before making those decisions, look beyond your profit.

Ask yourself:

  • How much cash is actually available?
  • Which customers still owe us money?
  • What bills and loan payments are coming due?
  • Are payroll and tax obligations covered?
  • Are we setting aside cash for fourth-quarter estimated taxes due in January?
  • Are we making spending decisions based on current, reconciled numbers?
  • Will we have enough cash available heading into January?

A profitable October doesn’t automatically guarantee a comfortable December. That’s why cash flow planning matters.

Accurate Bookkeeping Makes Cash Flow Easier to Understand

QuickBooks can produce useful reports, but reliable reporting requires more than entering transactions. Your financial records need to be reviewed, categorized correctly, and reconciled regularly.

A consistent monthly bookkeeping process helps you spot missing information, identify unusual balances, and understand what your numbers actually mean. It also makes conversations with your accountant and other financial advisers more productive.

Instead of spending time figuring out what happened three months ago, you can focus on what needs to happen next. That’s the real value of keeping your books current.

Emerald Consulting Helps You Understand the Numbers Behind Your Business

At Emerald Consulting, we help small and mid-sized businesses get more from QuickBooks through setup, troubleshooting, bookkeeping review, reconciliation, and ongoing remote bookkeeping services.

We understand that most business owners don’t want to spend their evenings figuring out why their Profit and Loss report doesn’t match their bank balance. They want financial information they can trust.

Our remote bookkeeping services can help keep your QuickBooks records organized and current so you have a clearer picture of your business.

Your business can be profitable and still run short on cash. The goal is to understand both numbers before they become a problem.

Contact Emerald Consulting for a free 30-minute needs assessment.

Frequently Asked Questions

Why does QuickBooks show a profit when I have no money in the bank?

Profit measures income minus expenses under the accounting method used. Your bank balance is also affected by customer payment timing, loan principal payments, inventory and asset purchases, sales tax payments, owner distributions, and other transactions that may not appear as expenses on your Profit and Loss report.

Does a QuickBooks Profit and Loss report show cash flow?

No. Even when you run a cash-basis Profit and Loss report, it doesn’t capture every movement of money into or out of your business. Review your Balance Sheet and Statement of Cash Flows for additional insight.

Should my business use cash or accrual accounting?

It depends on your business size, industry, and tax situation. Cash basis is simpler, while accrual basis gives a more complete picture of what you’ve earned and what you owe. Your tax professional can help you choose the method that fits your business.

How often should I review my QuickBooks financial reports?

At least monthly, after transactions have been reviewed and accounts reconciled. Businesses with tighter cash flow may benefit from reviewing available cash, expected receipts, and upcoming payments weekly.
QuickBooks monthly bookkeeping dashboard helping a small business owner review financial reports

QuickBooks Monthly Bookkeeping: Your April Advantage After Tax Season

Tax season is over, but your numbers still matter. QuickBooks monthly bookkeeping helps you turn tax-time stress into clear data you can use all year. When your books stay current every month, April becomes a launchpad for better decisions instead of a reset button.

What QuickBooks Monthly Bookkeeping Means

QuickBooks monthly bookkeeping is a simple idea. You keep your QuickBooks file updated, reconciled, and reviewed every month instead of once or twice a year. Each month, your activity is entered, checked, and organized so your reports match what is really happening in your business.

With this approach, you always know:

  • What you earned and spent last month.
  • Which customers still owe you money.
  • How much cash you can safely use.
  • Whether your business is on track with your goals.

For small businesses, that level of clarity is not a luxury. It is a foundation for smart choices.

Why April Is the Best Time to Start

April is a turning point. You just finished your tax return and saw a clear snapshot of last year. QuickBooks monthly bookkeeping lets you use that insight right away instead of waiting until next tax season.

In April, you can:

  • Compare this year’s first‑quarter results to last year.
  • Adjust prices, spending, or hiring plans based on real numbers.
  • Fix any gaps your CPA noticed in your records.

When you begin monthly bookkeeping now, the rest of the year feels calmer. You are not guessing at profits or scrambling for documents when deadlines come around again.

What a Monthly QuickBooks Workflow Looks Like

A strong QuickBooks monthly bookkeeping routine follows a clear pattern. Each month, your bookkeeper or your team can complete the same set of steps so nothing falls through the cracks.

A typical workflow includes:

  • Importing or entering all bank, credit card, and payment app transactions.
  • Reconciling each account so QuickBooks matches your bank statements.
  • Categorizing income and expenses using a clean chart of accounts.
  • Reviewing open invoices and sending reminders for unpaid balances.
  • Running core reports like Profit & Loss, Balance Sheet, and A/R Aging.

With Emerald Consulting, these steps are handled for you through our QuickBooks services and monthly bookkeeping support, so you do not have to fit “do the books” into an already full schedule.

Decisions You Can Make With Up‑to‑Date Books

Once QuickBooks monthly bookkeeping is in place, your reports stop being static documents. They become decision tools.

Here are a few questions you can answer quickly in April and beyond:

  • Can I afford to hire a part‑time employee this summer?
  • Which services or products are driving most of my revenue?
  • Are my software and subscription costs creeping up?
  • Do I have enough cash to invest in new equipment?

Because QuickBooks organizes your data by account, customer, and time period, your monthly bookkeeping lets you slice the numbers in different ways. You can spot trends early instead of reacting after the fact.

How Emerald Consulting Supports QuickBooks Monthly Bookkeeping

You do not have to manage all of this alone. At Emerald Consulting, QuickBooks is our specialty. We help small businesses set up or clean up their QuickBooks file, then keep it current through ongoing monthly bookkeeping services.

Our support can include:

  • Reviewing your QuickBooks setup and chart of accounts.
  • Handling monthly reconciliations and transaction entry.
  • Providing monthly report reviews in plain English.
  • Suggesting simple process tweaks that save you time.

If you are ready to use QuickBooks monthly bookkeeping to your advantage this April, our team can walk you through the next steps and create a routine that fits the way you work.

Small business bookkeeping workspace with organized financial records

Small Business Bookkeeping: Start the New Year With Clean Books

Small business bookkeeping is easiest—and most effective—when it’s handled in January. This is the one month business owners still have time to fix last year’s mistakes before tax season pressure hits.

If last year ended with uncategorized expenses, missing receipts, or balances that didn’t match the bank, you’re not behind—you’re normal. But waiting until March or April guarantees stress, higher costs, and messy reports.

Starting the year with clean books gives you clarity, confidence, and control over your business finances.

What Clean Small Business Bookkeeping Really Means

Clean small business bookkeeping is not just data entry. It means:

  • Bank and credit card accounts fully reconciled
  • Income and expenses categorized correctly
  • Personal transactions removed from business accounts
  • Accurate opening balances for the new year

If any of these are off, your financial reports are unreliable—and bad data leads to bad decisions.

Why January Is the Best Month for Small Business Bookkeeping

January bookkeeping sets the tone for the entire year. When your books are accurate from day one:

  • Cash flow is easier to track
  • Monthly reports actually make sense
  • Tax preparation becomes smoother
  • Business decisions are based on real numbers

January is also the ideal time to review your setup in QuickBooks, including your chart of accounts and automation rules. The IRS also recommends keeping organized financial records year-round, not just at tax time (see IRS small business recordkeeping guidelines).

January Small Business Bookkeeping Checklist

  • Reconcile all accounts through December 31
  • Review expense categories for accuracy
  • Confirm all income is recorded correctly
  • Separate personal and business expenses
  • Lock the prior year once books are clean

This one-time cleanup prevents accidental changes later and keeps reports consistent.

The Cost of Delaying Bookkeeping Until Tax Season

When small business bookkeeping is postponed until March or April:

  • Accounting and tax prep fees increase
  • Errors take longer to correct
  • Deductions are easier to miss
  • Stress multiplies fast

January cleanup costs less—in time, money, and sanity.

Start the Year With Confidence

Emerald Consulting helps small businesses clean up and maintain accurate bookkeeping so the year starts with clarity, not confusion. Strong bookkeeping isn’t optional—it’s foundational.


December bookkeeping checklist for small businesses using QuickBooks to close the year accurately

December Bookkeeping Checklist: Close the Year Strong with QuickBooks

December is not the month to wing it. It’s the month to get your numbers right.

This December bookkeeping checklist is built for small business owners who want to close the year clean, accurate, and tax-ready—especially if you use QuickBooks. A few focused steps now can save you time, money, and a January panic spiral that no amount of caffeine can fix.

If your books feel behind or messy, you’re not alone. What matters is fixing it before the year ends. This checklist walks you through exactly what to review, clean up, and lock down so you can start the new year with confidence instead of confusion.


1. Reconcile All Accounts (Non-Negotiable)

Start with the basics: reconciliation.

Before year-end, make sure every bank account, credit card, loan, and line of credit is reconciled in QuickBooks through November—and as far into December as possible. If balances don’t match, your reports are unreliable. Period.

Reconciliation is how you confirm that what QuickBooks shows actually matches reality. Skipping this step guarantees problems later, especially during tax prep.


2. Clean Up Uncategorized and Duplicate Expenses

Uncategorized transactions are a red flag, not a “later problem.”

Run your Uncategorized Expense report and clean it up before December closes. While you’re there, look for duplicate charges, misclassified expenses, and personal purchases mixed into business accounts.

The cleaner your books are now, the less you’ll pay your tax preparer—and the fewer questions you’ll have to answer in January.


3. Review Your Profit and Loss Report (Even If You’re Nervous)

Your Profit and Loss report tells the real story of your business.

In QuickBooks, review your P&L month by month and for the full year. Pay attention to rising costs, underperforming services, and trends that affect cash flow.

Avoiding this report doesn’t protect you. Understanding it helps you make better decisions in the new year.


4. Check Payroll and Prepare for 1099s

December is when payroll mistakes come back to haunt you.

Before the year ends, confirm employee details, payroll totals, and tax liabilities in QuickBooks. Review contractor payments and make sure vendor information is accurate so 1099s can be issued without delays.

Fixing payroll errors now is far easier than correcting them after filings begin.


5. Lock the Books After Final Review

Once everything is reconciled and reviewed, close the books in QuickBooks.

Closing the year prevents accidental changes and ensures your reports stay consistent for tax preparation. It’s a small step that protects the work you just did and keeps everyone on the same page.


A Word of Honest Advice

January is not the time to “get organized.”
December is.

If your books are behind, inconsistent, or causing stress, professional QuickBooks support can make a measurable difference. Emerald Consulting helps small businesses clean up their books, stay organized, and maintain accurate financial records year-round.

Clear books mean clearer decisions—and a stronger start to the new year.


Year-End Bookkeeping FAQs

What is a December bookkeeping checklist?
A December bookkeeping checklist is a year-end process that ensures all financial accounts, expenses, and payroll records are accurate before closing the books for tax season.

Why is December bookkeeping important for small businesses?
December bookkeeping reduces tax filing errors, lowers preparation costs, and gives business owners reliable financial reports before the new year begins.

Should I close my books in QuickBooks at year-end?
Yes. Closing your books in QuickBooks prevents accidental changes and ensures consistent reporting for tax preparation.

Can a bookkeeper help clean up QuickBooks before year-end?
Yes. A professional bookkeeper can reconcile accounts, correct expense categorization, and prepare clean reports before January.

Emerald Consulting provides QuickBooks bookkeeping services for small businesses in Texas and surrounding areas.

November bookkeeping checklist infographic showing icons for reconciling accounts, cleaning categories, reviewing financials, preparing payroll, and planning deductions

November Bookkeeping Checklist: Get Your QuickBooks Ready Before Year-End Hits

If you want to stay ahead of year-end chaos, your November bookkeeping checklist is the most important financial tool you’ll use this month. November gives you a quiet window to clean up QuickBooks, correct lingering issues, and prep for tax season before December turns everything into a scramble. This checklist walks you through the essential steps every small business should tackle right now to keep your books accurate and your workflow running smoothly.


1. Reconcile Every Account

Start your November bookkeeping checklist by reconciling all bank accounts, credit cards, payment apps, and loans. If money moves through it, reconcile it. Clean numbers now prevent costly surprises later and give you an accurate picture of your cash flow heading into the new year.

2. Clean Up Categories & Vendors

Fix duplicate vendors, correct miscategorized expenses, and clear out old “Ask My Accountant” entries. A clean chart of accounts ensures your financial reports reflect the real story of your business.

3. Review Your Profit & Loss

Use your P&L to pinpoint what’s working and what’s draining cash. November is the ideal time to make strategic decisions, adjust spending, or plan investments before year-end deadlines.

4. Prepare Payroll & 1099s

Gather W-9s, verify employee and contractor information, and review payments to ensure proper classification. Getting this ready now makes January 1099 filing much easier.

5. Maximize Year-End Deductions

Your November bookkeeping checklist should end with a strategic tax review. If you need equipment, software, or supplies, November is the perfect month to plan those deductible purchases.

Need help with QuickBooks cleanup or year-end prep? Emerald Consulting is here to make bookkeeping easier, cleaner, and stress-free.

Laptop displaying QuickBooks year-end reconciliation dashboard with coffee cup, October checklist, and fall leaves on a wooden desk — symbolizing organized bookkeeping and seasonal preparation.

Getting Ready for Year-End Reconciliation in QuickBooks

October is the perfect time to begin your QuickBooks year-end reconciliation—before the holiday rush hits and year-end deadlines close in.

At Emerald Consulting Inc., we’ve seen the difference preparation makes. Business owners who start early finish the year with clarity, confidence, and accurate books. Those who wait often spend their December evenings sorting through statements, chasing invoices, and wondering where that $300 “miscellaneous” charge came from.

Think of October as your “pre-close” month — a strategic chance to fine-tune your QuickBooks bookkeeping before year-end demands take over.

Here’s how to get ahead now and ensure your QuickBooks year-end reconciliation goes smoothly:


1. Reconcile All Accounts Monthly — Not Just at Year-End

Consistent reconciliation is the foundation of accurate QuickBooks bookkeeping. Compare your balances to your bank statements each month to spot discrepancies early.
If you wait until December, small errors multiply. Begin now, and you’ll save hours when tax season arrives.

👉 Need a refresher? Visit the QuickBooks Reconciliation Guide on Intuit’s website for step-by-step details.


2. Review Undeposited Funds and Open Invoices

Your Undeposited Funds account shouldn’t hold forgotten payments. Review and clear out lingering entries. Then, check your open invoices and send reminders to clients with unpaid balances.
This proactive step boosts Q4 cash flow and sets you up for a stronger finish.

(Tip: Learn more about invoicing in QuickBooks from our post How to Keep Your Business Books Healthy All Year Long.)


3. Categorize and Clean Up Expenses

Review your expense categories for accuracy. Reclassify anything marked as “Ask My Accountant” or “Miscellaneous.”
Accurate categorization keeps your QuickBooks year-end reconciliation clean and makes tax prep faster.


4. Update Vendor Information and 1099 Settings

Before the 1099 deadline sneaks up, verify vendor details and tax IDs. QuickBooks lets you tag 1099 vendors in bulk, saving you hours later.
Taking care of this now prevents January stress.


5. Create a Year-End Checklist

Prepare a checklist that includes reconciliations, payroll reports, and core financial statements like your Profit & Loss, Balance Sheet, and Cash Flow report.
You’ll stay organized—and next year, this list becomes your ready-made guide.


Why Starting Now Matters

✅ Accuracy: Prevent reporting errors before they snowball.
✅ Organization: Clean data ensures seamless reports.
✅ Efficiency: Updated vendor info simplifies tax season.
✅ Cash Flow: Cleared invoices strengthen your financial position.


At Emerald Consulting Inc., we help business owners master their QuickBooks year-end reconciliation through automation, cleanup, and monthly bookkeeping support.
Schedule your free 30-minute consultation and finish 2025 with organized, audit-ready books.cords.

QuickBooks automation for year-end bookkeeping Q4 planning

Optimizing Your Q4 with Smart QuickBooks Automation

As we approach the final months of 2025, it’s the perfect time to prepare your books for a strong finish—and a seamless transition into next year. At Emerald Consulting, we’ve helped countless clients streamline their financial operations with precision, accuracy, and foresight. Here are four strategic ways to boost efficiency and insight using QuickBooks before year’s end:

1. Automate Your Year-End Reminders

Don’t let late invoices slow your cash flow. QuickBooks lets you schedule built-in email reminders—30, 15, and 5 days before due dates—to prompt timely payments. In Q4, consider customizing reminder content with a seasonal touch (“Let’s wrap up the year smoothly—your invoice is due soon!”) to maintain engagement and goodwill.

2. Leverage Class & Location Tags for 2025 Performance Tracking

If you haven’t already, start tagging transactions by Class and Location now. This enables easy comparison between business segments—online vs. in-store, regional branches, or product lines. You’ll gain refined insight into what’s working (and what needs adjustment) before closing out the year—just as we’ve advised in earlier posts. Instagram+9Emerald Consulting Inc.+9Emerald Consulting Inc.+9

3. Schedule Quarterly Data Backups & QuickBooks Updates

With tax season around the corner, ensure your data is safeguarded. Set automated backups—cloud or local—for all Q4 data, and install QuickBooks updates promptly. Staying current avoids surprises from patches or new features that roll out near fiscal year-end. (This echoes our earlier recommendation on weekly backups—adapting it for a year-end cadence for added protection.) Emerald Consulting Inc.+1

4. Set Up Year-End Reports & Custom Dashboard Insights

Quarterly planning becomes smoother when real-time, accurate data is at your fingertips. Use QuickBooks to generate your year-to-date Profit & Loss, Balance Sheet, and Cash Flow reports. Build a custom dashboard highlighting your top 3 KPIs—such as gross margin %, net sales, and account receivables aging—to guide Q1 2026 strategy. You’re building on the automated workflows we’ve championed in past posts. Emerald Consulting Inc.


Why It Matters

  • Sharper cash flow visibility: Automated reminders mean fewer overdue payments.
  • Segmented clarity: Class and Location tagging ensures you understand where profits—and challenges—are coming from.
  • Year-end readiness: Backups and updates protect against disruptions during filing season.
  • Strategic insight: Dashboards and custom reports give you the foresight to plan, not just react.

Ready to Optimize Your Q4?

Emerald Consulting is here to help you put these smart practices into action—accurately, efficiently, and stress-free. Whether you’re looking for automation support, custom reporting, or year-end cleanup, our team is ready with expertise in QuickBooks Online, Desktop, Enterprise, and Trusted Remote Bookkeeping Services. Emerald Consulting Inc.+1Emerald Consulting Inc.QuickBooks+3Emerald Consulting Inc.+3Emerald Consulting Inc.+3

Let’s make 2025 your most organized, insightful year yet. Get in touch for a free 30-minute consultation tailored just for you!

Audrey Duke – 2025 QuickBooks ProAdvisor Award Winner | Emerald Consulting Inc.

Audrey Recognized with 2025 QuickBooks ProAdvisor Award

We’re excited to celebrate a major achievement—Audrey from Emerald Consulting INC has been named a 2025 QuickBooks ProAdvisor Award recipient!

This prestigious recognition honors top-tier QuickBooks professionals across the country who exemplify excellence, leadership, and dedication in the bookkeeping and accounting space. Audrey’s work ethic, technical expertise, and client-first approach have made her an invaluable part of the Emerald team—and this award is a well-deserved recognition of her impact.

Here’s why Audrey stands out:

✅ Deep expertise in QuickBooks Online and Desktop
✅ Reliable, responsive client support
✅ A sharp eye for detail and financial accuracy
✅ Dedication to continuous learning and best practices

We recently had the privilege of celebrating this milestone with her—and we’re excited to share the moment with you too!

Please join us in congratulating Audrey on this outstanding accomplishment. Her excellence helps keep Emerald Consulting INC a trusted name in modern bookkeeping solutions.

Laptop showing QuickBooks dashboard with bookkeeping icons and Emerald Consulting logo

QuickBooks Bookkeeping Tips to Transform Your Small Business

IQuickBooks bookkeeping tips are essential for any small business owner looking to gain real-time financial clarity. At Emerald Consulting Inc., we guide you through proven methods to organize your books, automate workflows, and make data-driven decisions from day one.

1. QuickBooks Chart of Accounts Management

A tidy chart of accounts lays the groundwork for accurate QuickBooks bookkeeping tips. Use clear naming conventions (e.g., “Sales–Retail” vs. “Sales–Wholesale”) and group similar expense categories. This structure helps you generate focused reports in seconds.

2. Monthly QuickBooks Reconciliation Best Practices

Set aside 10–15 minutes each month for bank reconciliation. Comparing your QuickBooks balance to your actual bank statements catches duplicate entries, overlooked fees, and miscategorized transactions before they snowball.

3. Automate Invoice Reminders in QuickBooks

One of the top QuickBooks bookkeeping tips is to automate your payment reminders. Schedule courteous emails 7, 14, and 21 days after an invoice is due so you can focus on growing revenue instead of chasing late payments.

4. Use Classes & Locations for Financial Reporting

For businesses with multiple product lines or storefronts, leverage QuickBooks’ Classes and Locations features. Tag every transaction by class (e.g., “Online Sales”) or location (e.g., “Dallas Office”) to unlock segmented profit-and-loss insights.

5. Backup QuickBooks Data & Keep Software Updated

Protect your financial data with weekly backups—cloud or local—and install QuickBooks updates promptly. Staying current ensures you always benefit from the latest security patches and feature enhancements.

Learn more about our Bookkeeping Services.

Visit the official QuickBooks site for product details.

Clean, spring-themed workspace with laptop displaying QuickBooks Clean-Up dashboard, checklist, calculator, and flowers—ideal setting for financial organization.

QuickBooks Clean-Up: Spring Is the Best Time to Reboot Your Books

Spring cleaning isn’t just for closets—your QuickBooks file deserves a refresh too. As we move through May 2025, now’s the perfect time to give your books the attention they need to stay accurate, organized, and audit-ready.

At Emerald Consulting, we specialize in bookkeeping solutions that go beyond just keeping up—we help businesses get ahead. A QuickBooks clean-up not only improves reporting accuracy but also helps business owners make better decisions throughout the rest of the year.

Here’s why May is the ideal month for a financial tune-up:

✅ Post-tax season clarity
Now that tax season is behind you, it’s easier to spot discrepancies, duplicates, or miscategorized transactions. Use this breathing room to catch up and clean up.

✅ Prep for Q2 and Q3 growth
An up-to-date QuickBooks file sets the stage for strategic planning. With accurate data, you’ll be better equipped to manage cash flow, track expenses, and forecast revenue.

✅ Avoid costly errors
Misposted entries and unreconciled accounts can throw off your entire financial picture. Cleaning up your QuickBooks now helps prevent surprises at year-end.

Whether you’re managing your own books or working with a bookkeeper, now is the time to review your chart of accounts, reconcile bank statements, and remove old or inactive vendors and customers.

Need help with a QuickBooks clean-up? Emerald Consulting offers personalized support to get your books back on track. Let’s make 2025 your most organized year yet.

📞 Ready to reboot your books? Contact us today for a QuickBooks check-up tailored to your business.